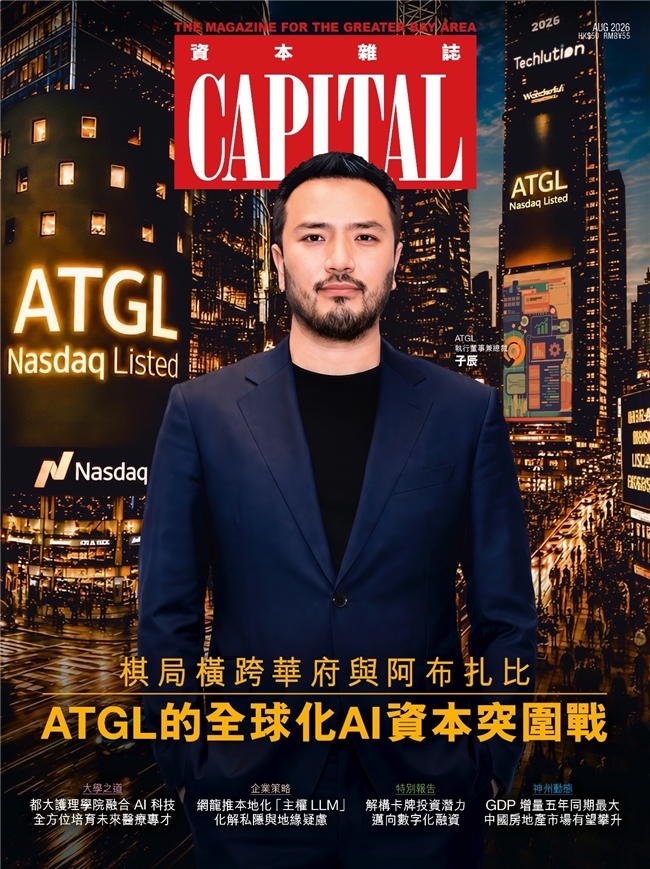
(Anthony Tsang, president and executive director of ATGL, featured on the August 2026 cover of CAPITAL magazine.)
Source Note: Inspired in part by CAPITAL magazine’s August 2026 cover story, this article independently reinterprets ATGL’s development through an industry and investor‑focused lens.
AlphaClaw gives the Nasdaq‑listed technology company a clearer platform strategy, but customer adoption, recurring revenue and capital discipline will determine whether the transition creates lasting value.
The enterprise artificial intelligence market is moving beyond the initial excitement surrounding general‑purpose large language models. For investors, the more important question is now whether AI companies can turn technical capabilities into secure, repeatable and economically viable business applications.
That shift provides the broader context for Alpha Technology Group Limited’s latest strategic repositioning.
The Nasdaq‑listed Hong Kong technology company announced on June 25, 2026 that its principal business activities would focus on Exclusive Large Language Model solutions, AlphaClaw AI Agents and the AlphaClaw AI Agent Marketplace. The announcement represents a move away from ATGL’s historical identity as a provider of project‑based IT development, cloud services and AI‑powered optical character recognition solutions. (sec.gov)
The strategy is commercially relevant. However, its investment significance will depend less on the language of AI innovation and more on the company’s ability to establish measurable adoption, recurring revenue and a defensible market position.
A more focused enterprise‑AI proposition
AlphaClaw consists of two connected offerings.
The first is a suite of AI agents designed to support enterprise functions including customer service, human resources, sales and document processing. According to ATGL, most of the underlying skills are built using the company’s own Exclusive LLM technology and can be adapted to specific customer requirements.
The second is the AlphaClaw AI Agent Marketplace, through which ATGL intends to distribute its own agents and potentially host agents or specialised skills developed by third‑party providers under revenue‑sharing arrangements. (sec.gov)
Together, these offerings give ATGL a more coherent commercial structure than a conventional project‑based IT services model.
Custom software projects generally depend on individual contracts, engineering capacity and one‑time implementation revenue. An agent platform, by contrast, could potentially generate a combination of deployment fees, subscriptions, usage‑based revenue and marketplace commissions.
That distinction is important—but it remains a strategic possibility rather than a demonstrated financial outcome.
For the marketplace model to become meaningful, ATGL will need more than a catalogue of internally developed tools. It will need active enterprise customers, credible third‑party contributors, reliable quality controls and enough transaction volume to create a functioning commercial ecosystem.
The opportunity lies in applied AI
ATGL does not need to compete directly with the world’s largest foundation‑model developers to build a viable business.
Its more realistic opportunity may lie in applied enterprise AI: adapting models to specific workflows, integrating them with existing systems and providing organisations with greater control over data, security and operational processes.
This approach could be particularly relevant to companies and public‑sector organisations that want to deploy AI without relying entirely on generic consumer‑facing platforms. ATGL describes AlphaClaw as a secure and customisable environment intended for commercial applications, although investors will ultimately need customer deployments and performance data to evaluate those claims. (sec.gov)
The company’s industry collaborations may offer early indications of how that strategy could be applied. On June 16, 2026, ATGL announced a partnership with Wai Yuen Tong Medicine to develop an AI‑ and blockchain‑based traceability system for traditional Chinese medicine. The project illustrates a potential vertical use case combining data management, product verification and industry‑specific technology. (sec.gov)
ATGL has also previously established AlphaMind Lab with the Hong Kong University of Science and Technology to conduct research into more efficient development of dedicated AI models. While research partnerships can support technical credibility, their commercial value will depend on whether the resulting intellectual property produces deployable products, customer contracts or licensing opportunities. (sec.gov)
Commercial evidence is now the central question
For institutional investors, product descriptions alone will not be sufficient.
The next stage of the ATGL investment case will depend on measurable operating indicators, including:
‑ the number of paying AlphaClaw customers;
‑ the distinction between pilot projects and full commercial deployments;
‑ contract values and revenue‑recognition schedules;
‑ subscription or usage‑based revenue;
‑ customer retention and expansion;
‑ gross margins associated with AI deployments;
‑ marketplace participation by third‑party developers; and
‑ the cost of acquiring and supporting enterprise customers.
These indicators would allow investors to distinguish between a promising technology concept and a scalable commercial platform.
Until such data are disclosed, AlphaClaw should be viewed as an early‑stage strategic platform rather than an established growth engine.
The financial starting point remains challenging
ATGL’s historical financial results underline the scale of the transition.
For the fiscal year ended September 30, 2025, the company reported revenue of approximately US$950,541, a decline of 40.13% from the prior fiscal year. Gross profit fell to approximately US$467,577. ATGL also reported a net loss of approximately US$9.05 million, although that figure included approximately US$5.56 million in share-based compensation and approximately US$1.74 million in impairment charges related to goodwill and intangible assets. (sec.gov)
These results mainly reflect the company’s historical operations and pre-date the formal positioning of AlphaClaw as a principal business activity. They therefore do not provide a complete measure of the new strategy’s potential.
At the same time, they establish a demanding baseline. The AI transition will need to produce not only revenue growth, but also an improvement in revenue quality, operating efficiency and cash generation.
As of September 30, 2025, ATGL held approximately US$3.97 million in cash and cash equivalents and reported approximately US$1.69 million of net cash used in operating activities during the fiscal year. The company stated that its available financial resources were expected to meet anticipated cash needs for at least 12 months from the date of its annual report. (sec.gov)
Investors should consequently monitor development expenditure, hiring, customer-acquisition costs and any future debt or equity financing. A platform strategy can offer greater scalability, but building the platform, supporting enterprise customers and attracting external developers can also require sustained investment before meaningful recurring revenue emerges.
A credible strategy that now requires validation
ATGL’s strategic repositioning reflects a broader change in the AI industry.
The initial competition to build increasingly powerful models is being followed by a commercial race to deploy AI inside real business processes. Companies that can combine specialised models, workflow integration, data protection and reliable enterprise support may be able to capture value without competing directly with the largest global technology platforms.
AlphaClaw gives ATGL a clearer position within that market. The combination of proprietary agents, customisable enterprise applications and a curated marketplace offers a more scalable narrative than the company’s historical project‑based services.
But a clearer narrative is not the same as a proven business model.
For professional investors, the most important signals will be customer adoption, recurring revenue, gross‑margin development, cash discipline and evidence that ATGL’s partnerships and strategic initiatives contribute directly to commercial growth.
The company has now defined the direction of its transformation. The next task is to demonstrate that the technology can produce repeatable business outcomes.
Investor takeaway
ATGL has established a more focused enterprise‑AI strategy through AlphaClaw, but the investment case will depend on whether the company can convert its technology, partnerships and platform ambitions into disclosed customer adoption, recurring revenue and sustainable cash generation.